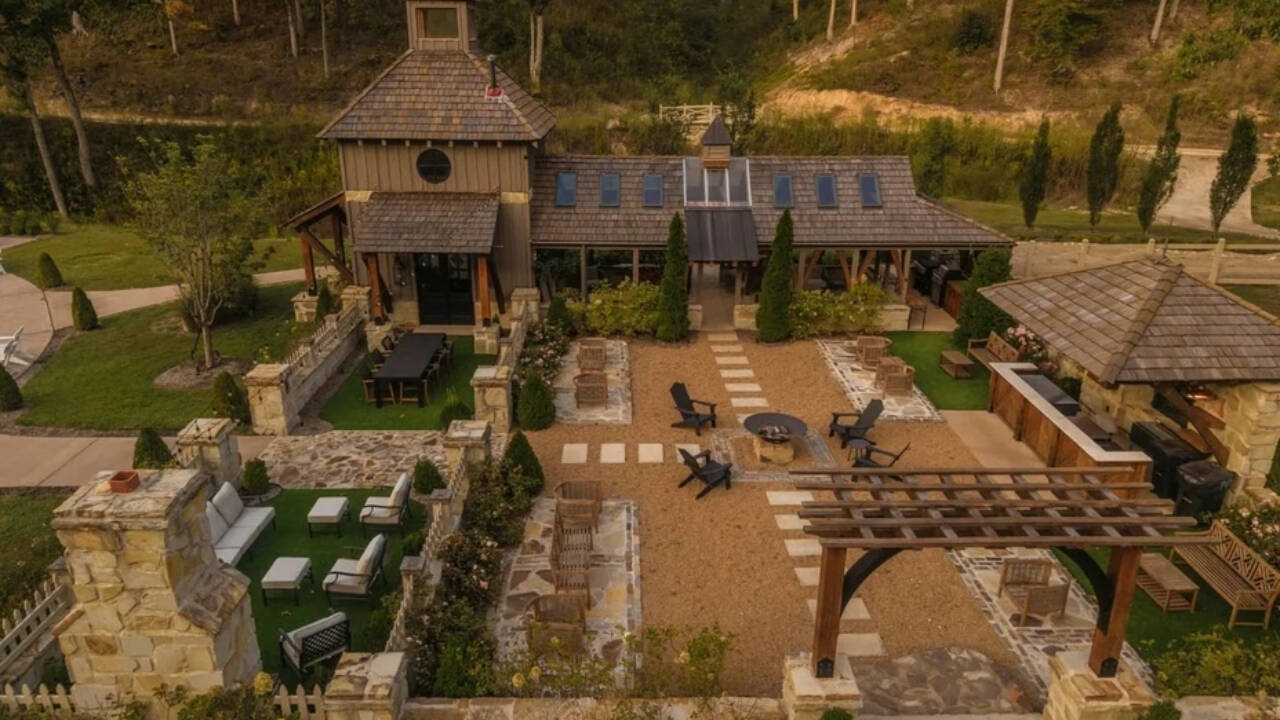
High-end residential real estate transactions rarely function as standard consumer purchases. Instead, they operate as heavily leveraged capital allocation plays, where asset appreciation is driven by localized structural interventions rather than broad macroeconomic beta. When an ultra-luxury property transitions from a $6.8 million acquisition to a $19.9 million valuation following a substantial physical build-out, the delta cannot be explained by inflation or passive market drift. It represents an engineered transformation of square footage utility, scarcity creation, and architectural positioning.
Evaluating this scale of value accretion requires analyzing the mechanics of capital expenditure within niche geographic submarkets. Luxury buyers do not purchase raw land or static structures; they purchase finalized architectural ecosystems.
The Cost Basis and Capital Expenditure Mechanics
The initial acquisition price establishes the floor of the investment thesis. In the case of high-value acreage or legacy estates, the purchase of the underlying land and primitive structure represents the raw input cost. However, the subsequent capital expenditure phase is where the risk and return profile diverges sharply from traditional residential models.
A massive physical build-out involves three distinct capital sinks:
- Hard construction costs, encompassing structural framing, premium finishes, and specialized engineering.
- Soft costs, including zoning variances, architectural permits, structural engineering reviews, and specialized design consultation fees.
- Carrying costs, which accumulate via property taxes, insurance, and the opportunity cost of tied-up liquidity during multi-year development cycles.
When capital expenditure outlays are stacked on top of a low-basis acquisition, the total invested capital creates a new baseline cost. The market valuation does not automatically track dollar-for-dollar with construction spend. Instead, the market applies a multiplier based on the scarcity of the finished product. If the local market lacks comparable turnkey compounds, the newly completed estate captures a monopoly rent on quality, pushing valuations past simple cost-plus calculations.
Micro-Market Liquidity and Scarcity Pricing
Macroeconomic indicators such as national interest rates or regional housing indices fail to capture the pricing dynamics of ultra-prime real estate. These submarkets operate on idiosyncratic supply constraints.
Properties valued near the twenty-million-dollar threshold face an extremely thin buyer pool. Standard market comparables often break down because no two ultra-custom estates share identical architectural profiles, square footage specifications, or amenity configurations. Value is therefore derived through replacement cost combined with a premium for immediate occupancy of a bespoke asset.
When a property is re-introduced to the market at a significantly elevated valuation after a multi-year transformation, it tests the upper bound of local buyer demand. The success of such a pricing strategy depends on eliminating execution risk for the buyer. Ultra-high-net-worth purchasers prioritize time over capital efficiency. By absorbing the multi-year friction of zoning, construction delays, and contractor management, the developer or investor unlocks a liquidity premium that standard residential properties cannot command.
Risk Asymmetry in Luxury Asset Redevelopment
The spread between a modest entry price and an apex exit valuation is wide precisely because the execution risk is severe. Luxury real estate development carries specific failure modes that must be factored into any rigorous analysis.
- Over-improvement risk occurs when capital is sunk into hyper-specific architectural or interior choices that do not appeal to the broader pool of ultra-prime buyers. When finishes are too idiosyncratic, the target demographic shrinks from a narrow pool to an absolute micro-niche, drastically lengthening days-on-market.
- Timeline expansion directly erodes internal rates of return through compounding carrying costs and shifts in macroeconomic liquidity cycles.
- Construction inflation can quickly distort initial project models, turning anticipated margins into thin or negative yields if soft and hard costs outpace appreciation rates.
Strategic Asset Management Blueprint
To replicate or evaluate high-value residential transformations without relying on speculative market assumptions, capital deployment must follow a strict operational hierarchy.
First, secure land parcels with structural or locational moats that cannot be replicated—such as exceptional topography, privacy barriers, or restricted zoning overlays. Second, align the scale of the capital expenditure precisely with the absolute ceiling of the local submarket's historical transaction data. Building a structure whose total basis exceeds the ceiling of neighboring comparable sales by an order of magnitude introduces catastrophic downside exposure. Third, treat the development lifecycle as an industrial project, utilizing fixed
Asset Arbitrage and Capital Expenditure Yield in Luxury Real Estate Markets
business, lifestyle
High-value real estate transactions are frequently misread through the lens of aesthetic appreciation or headline-grabbing gross valuations. When a Tennessee luxury estate lists or returns to market at a massive valuation like 19.9 million dollars following a cumulative capital expenditure of 6.8 million dollars, the transaction ceases to be a simple housing market indicator. It becomes a case study in asymmetric asset transformation, capital allocation efficiency, and the structural friction of illiquid markets.
Analyzing this transaction requires stripping away the narrative of luxury lifestyle marketing and examining the fundamental mechanics of real estate development: acquisition cost, capital expenditure efficiency, holding costs, and the liquidation premium. Without a rigorous framework, market participants conflate sunk costs with market value, leading to severe pricing errors and prolonged inventory stagnation.
The Capital Stack and Cost-Basis Economics
Every real estate development project relies on a static baseline: the initial purchase price plus the cumulative capital deployed for structural improvements, zoning adjustments, and finishing. However, the market does not reward capital expenditure on a linear, dollar-for-dollar basis.
When analyzing a property that underwent a 6.8 million dollar build-out, the analytical mistake is assuming that every dollar spent increased the asset baseline by an equivalent amount. In high-end residential engineering, capital expenditure splits into two distinct categories: functional value and idiosyncratic value.
Functional value includes structural integrity, mechanical systems, layout optimization, square footage expansion, and compliance updates. These expenditures protect the asset's floor value by ensuring it meets modern engineering and security standards.
Idiosyncratic value includes bespoke finishes, specialized architectural styling, luxury amenities tailored to a specific owner, and non-standard floor plans. These expenditures often suffer from immediate depreciation upon installation because they appeal to a vanishingly small segment of potential buyers.
Total Capital Deployed = Initial Acquisition Cost + Functional CapEx + Idiosyncratic CapEx
Market Valuation Realization = Initial Acquisition Cost + (Functional CapEx * Marginal Yield) + (Idiosyncratic CapEx * Discount Factor)
When an estate commands a 19.9 million dollar price tag after heavy capital injections, the pricing strategy must account for the diminishing marginal returns of luxury build-outs. The market does not pay a premium for over-improvement; it prices the asset based on comparable replacement cost and the net present value of utility for the buyer pool.
The Liquidity Discount in Ultra-Prime Niches
Real estate liquidity is inversely proportional to asset valuation. As a property moves into the ultra-prime tier, the total addressable market of qualified buyers shrinks exponentially.
In a traditional housing market, pricing is discovered through high-frequency transactions and deep comps. In the ultra-prime tier, transactions are rare, idiosyncratic, and heavily influenced by macroeconomic liquidity cycles, interest rate regimes, and regional wealth migration patterns.
When a property is positioned at nearly 20 million dollars, the seller faces three primary structural constraints.
The first constraint is the buyer pool bottleneck. The number of individuals possessing the liquid net worth required to acquire a 20-million-dollar residential asset without over-leveraging is remarkably small. Within a specific regional market like Tennessee, this pool contracts further, as ultra-high-net-worth buyers often distribute their portfolios across primary financial centers, coastal hubs, or international properties.
The second constraint is the opportunity cost of capital. For a buyer deploying 20 million dollars into a residential asset, the annual carrying cost—comprising property taxes, maintenance, security, insurance, and the forgone yield of alternative investments—represents a substantial financial commitment. If an alternative asset class offers a predictable 6 to 8 percent yield, holding a non-income-producing luxury estate carries a hidden annual cost of over one million dollars in lost yield alone.
The third constraint is financing friction. Jumbo and ultra-jumbo mortgages for bespoke luxury estates often require strict underwriting, massive cash reserves, and significant down payments. This forces reliance on cash transactions or complex structured finance, which inherently limits market velocity.
Market Positioning and Pricing Mechanics
Pricing an asset of this scale requires an understanding of psychological anchoring and competitive displacement. When a property re-enters the market at a high valuation, it competes not just with local inventory, but with national and global luxury alternatives. A buyer with 20 million dollars can choose between a sprawling estate in Tennessee, a penthouse in a major financial hub, or a coastal property.
Therefore, the asset must clear a strict comparative utility hurdle.
Comparative Utility = (Functional Square Footage * Location Multiplier) - Friction Cost of Customization
If the build-out was heavily customized to the previous owner's tastes, the incoming buyer must factor in the cost of demolition and redesign. This introduces a negative adjustment to the asking price. Conversely, if the build-out created a turnkey compound with rare infrastructural advantages—such as complete privacy, extensive acreage, advanced security systems, and high-spec mechanical plants—the asset can justify a premium over raw replacement cost.
Strategic Execution and Downside Protection
Evaluating the viability of a 19.9-million-dollar exit strategy demands a focus on downside protection rather than speculative upside. In ultra-prime real estate, appreciation is a secondary outcome of macroeconomic inflation and supply scarcity; the primary objective of the capital allocation strategy is capital preservation.
Sellers and developers in this tier must avoid the trap of anchoring to cumulative historical costs. The market cares exclusively about current utility and future cash flow or utility generation. If the asset fails to move at the target price, the mechanism of correction is not incremental price reductions, but a fundamental reassessment of the target buyer profile.
Sustained inventory stagnation signals that the asset is mispriced relative to its functional utility within its specific geographic micro-market. To clear the asset, the pricing structure must align with the intersection of replacement cost and the liquidity threshold of the regional ultra-high-net-worth demographic.
Market participants who ignore these structural economic realities risk prolonged holding periods, escalating carrying costs, and eventual realization losses that far outweigh the initial capital expenditure miscalculations.