Executive announcements regarding fuel tax exemptions often obscure the underlying financial transmission mechanisms that determine actual operational relief. When an administration enacts a policy targeting reduced energy input costs for commercial transportation, the immediate headline figure rarely reflects the distributed economic reality across supply chains. Assessing the actual impact of tax-free red diesel requires moving past nominal savings metrics and evaluating the structural cost functions, distribution channels, and compliance constraints that govern commercial fleet operations.
The Cost Function of Commercial Fuel Inputs
Fuel represents one of the two largest variable cost centers for heavy-duty freight operators, typically sitting alongside labor as the primary determinant of operating margins. The standard commercial diesel price structure comprises base commodity cost, refining margins, distribution overhead, and federal or state excise taxes. When policy interventions remove specific tax components from specialized fuel grades, the financial adjustments ripple through distinct operational layers.
Red diesel, traditionally designated for off-highway applications such as agriculture, construction, and home heating, contains chemical markers distinguishing it from standard highway diesel. These markers exist purely for regulatory enforcement, preventing tax evasion by non-highway users. Extending eligibility for tax-free or reduced-tax red diesel to interstate or commercial over-the-road trucking shifts the regulatory boundary, but it introduces immediate friction points regarding vehicle engineering specifications, fuel storage infrastructure, and auditing protocols.
The claim of a fixed savings figure per fill-up relies on generalized tank capacities and average wholesale-to-retail tax differentials. However, commercial transport does not operate on averages; it operates on route-specific fuel burn rates, varying state-level tax credits, and dynamic fuel surcharge mechanisms embedded in shipper contracts.
Market Transmission and Shipper Carrier Dynamics
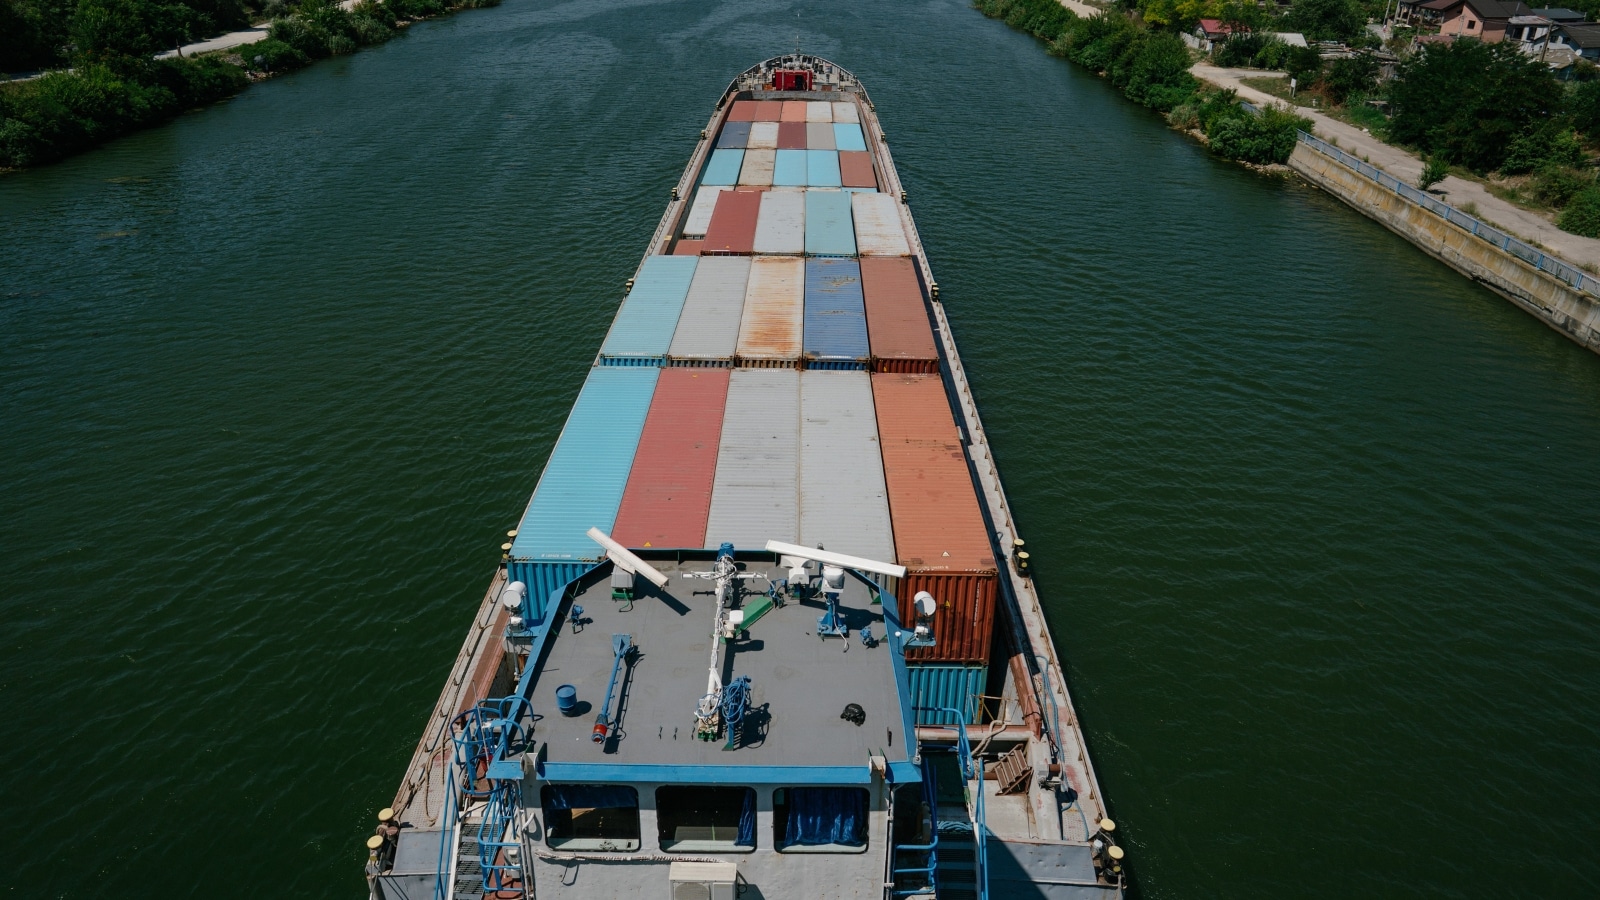
A fundamental error in evaluating fuel tax relief is assuming that input cost reductions translate directly into retained net margin for the carrier. The freight market operates under competitive pricing pressures mediated by fuel surcharge indices. Most long-haul carrier contracts include mechanisms that automatically adjust freight rates upward or downward based on the national average price of diesel fuel.
When a tax exemption lowers the out-of-pocket cost of fuel at the pump for the carrier, two economic forces immediately compete for that margin:
The first force involves shipper renegotiation. Large enterprise shippers monitor macro fuel indices closely. If federal policy structurally lowers diesel acquisition costs, shippers will rapidly apply downward pressure on base rates or fuel surcharge formulas to capture the efficiency gain. The carrier's net retention depends entirely on market concentration and bargaining power during contract renewal cycles.
The second force involves compliance overhead. Diverting off-highway fuel streams into standard over-the-road fleets requires adjusting logistics networks to access specific fueling depots that stock red diesel. If fleets must deadhead—drive unladen—to find compliant fueling infrastructure, the auxiliary labor and fuel burn can completely neutralize the per-gallon tax savings.
Regulatory Compliance and Enforcement Architecture
The transition from a restricted fuel classification to an expanded commercial exemption demands a rigorous examination of the regulatory apparatus. Tax-free fuels are historically monitored through strict auditing of stationary equipment, agricultural machinery, and localized plant operations.
When applied to mobile interstate commerce, the enforcement challenge multiplies exponentially. Fuel tax evasion historically costs federal and state treasuries billions of dollars annually. Introducing a dual-pricing or dual-tax structure for over-the-road commercial vehicles creates an immediate arbitrage opportunity. Unscrupulous operators face heightened incentives to misroute or illegally introduce dyed diesel into standard passenger vehicles or non-qualifying commercial fleets, forcing regulatory bodies to increase auditing frequency.
The administrative burden shifts directly to fleet management systems, which must maintain indisputable digital audit trails proving that every gallon of tax-free fuel consumed mapped strictly to eligible operational miles. The cost of software integration, specialized accounting, and potential audit exposure forms an unacknowledged capital expenditure that must be weighed against the nominal per-gallon relief.
Operational Constraints of Alternative Fuel Grades
Beyond regulatory and market transmission factors, operators must account for the chemical and logistical profile of the fuel itself. While red diesel and clear highway diesel are fundamentally the same distillate product prior to the addition of dye and specific marker chemicals, the physical supply chain handling them is segregated.
Fuel terminals maintain distinct storage tanks for taxed and untaxed products. In regions where commercial demand for red diesel spikes due to regulatory shifts, local terminal rack pricing and inventory availability can experience localized supply bottlenecks. If regional distribution nodes lack the pumping capacity to handle the surge in commercial demand, carriers will encounter fueling queues, increased asset downtime, and delivery delays that erode trip productivity.
Furthermore, jurisdictional complexity remains a major barrier. Federal tax exemptions do not automatically preempt state-level fuel excise taxes. While a federal order can eliminate or reduce federal highway tax liabilities, state fuel taxes often constitute the larger portion of the total tax burden at the pump. If state regulatory boards do not harmonize their tax codes with federal exemptions, carriers face a fragmented compliance landscape where savings realized at one terminal are negated crossing state lines.
Strategic Capital Allocation for Fleet Operators
Relying on policy-driven energy price fluctuations as a core strategy for margin expansion introduces severe vulnerability. Fleet management requires long-term capital allocation models that account for asset depreciation, aerodynamic efficiency, powertrain transition, and driver retention.
Operators who treat tax-related fuel savings as permanent structural improvements risk over-leveraging their balance sheets or under-bidding long-term contracts. A more rigorous analytical approach involves ring-fencing any realized tax savings exclusively for capital expenditures that permanently lower energy intensity, such as fleet electrification trials, predictive powertrain routing software, or advanced aerodynamic retrofits.
Deploy capital reserves into telemetry systems that optimize fuel burn through real-time grade and wind analysis rather than chasing transient legislative interventions. True operational resilience is achieved by decoupling fleet profitability from the volatility of tax policy through continuous efficiency gains across the entire transport vector.